Credit Card and Payment Processing Industry Overview: Stats, Trends, and Insights

Payment processing statistics tell different stories depending on whether you measure transactions, dollars, or consumer preferences. Cards handle frequent purchases. ACH moves much larger amounts. Cash remains relevant to customers who prefer it or keep it as a backup.
For businesses planning 2027, the useful question is how those patterns affect acceptance costs, customer choice, and payment operations. This guide separates the observation period from the publication year so that older measurements do not become new facts simply because a report has a recent title.
How the payment processing industry fits together
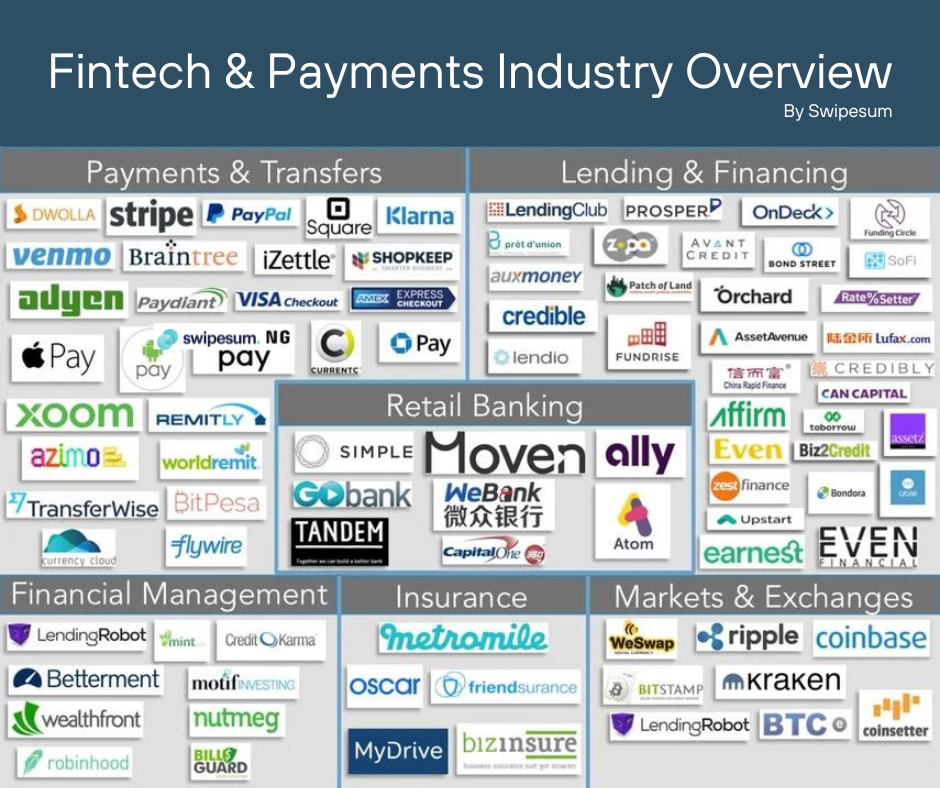
Start with the job each part of the system performs. The issuer provides the customer's card account. The merchant's acquiring relationship supports card acceptance and settlement. A processor handles transaction messages, and a payment gateway connects the payment experience to processing infrastructure. Networks connect participating institutions under their rules. One provider may perform several of these jobs.
The history of credit cards explains how that system developed. For the steps in an individual transaction, see our guide to credit card processing. A useful provider comparison considers both the economics and who owns each operating responsibility.

Payment processing statistics at a glance
- U.S. noncash payments: 236.6 billion; $140.01 trillion. Calendar 2024; national payments study. Source: Federal Reserve.
- Card share of noncash payments: 79% by number; 8% by value. Calendar 2024; excludes cash from the denominator. Source: Federal Reserve.
- ACH share of noncash payment value: 74%. Calendar 2024. Source: Federal Reserve.
- U.S. consumer cash share: 14% of payments. Consumer activity in 2025; reported in the 2026 Diary. Source: Federal Reserve Financial Services, printed p. 3.
- ACH Network activity: 9.3 billion payments; $25.6 trillion. Q3 2026; network totals. Source: Nacha.
- Same Day ACH growth: 36.7% increase in payment count. Q3 2026 compared with Q3 2025. Source: Nacha.
- RTP network activity: 422.2 million payments; approximately $1.679 trillion. January–September 2026; year to date. Source: The Clearing House.
These figures describe different populations and periods. They cannot be added together to produce a single market total. Dollar amounts describe payment value, not payment-provider revenue.
Cards dominate payment count; ACH dominates value
The Federal Reserve reports 120.6 billion debit card payments and 67.1 billion credit card payments in 2024. ACH transfers accounted for $104.06 trillion in value. Those measurements explain why a retail checkout and a business receivables operation can need very different payment strategies even within the same company. Source: national payment volumes.
Our interpretation: start a payment review with the transactions your business actually handles. Separate channels, payment methods, and ticket sizes before comparing prices. A rate that looks attractive on one transaction profile can produce a different result on another.
For a merchant, that means reviewing the statement alongside sales volume and transaction count. For a software platform, it means looking separately at merchant adoption, payment mix, and the economics of each supported method.
Cash usage and payment preference measure different things
The 2026 Diary of Consumer Payment Choice covers behavior in 2025. It reports an average of 47 payments per consumer per month. For in-person payment preference, debit led at 40%, followed by credit at 38% and cash at 16%. Cash represented 14% of actual payments, a different measure. Source: Diary, printed pp. 3 and 9.
Do not treat the preference ranking as your own sales mix. The Diary includes consumer payments such as bills and person-to-person transfers; your checkout has its own customer population. A restaurant, rural retailer, online subscription business, and B2B supplier should each test what their customers use and what accepting it costs. Our guide to choosing a retail payment solution provides a starting point for matching acceptance to the business.
Same Day ACH is growing, with a distinct role from instant payments
Nacha's October 20 release reports 470.4 million Same Day ACH payments in Q3 2026. B2B ACH payment count rose 9.7% year over year to nearly 2.3 billion. The data supports treating bank payments as a substantive part of payment planning. It does not show that every business should replace card acceptance. Source: Nacha Q3 2026 results.
For a business evaluating bank payments, our recommended comparison includes collection workflow, customer authorization, settlement timing, return handling, reconciliation, and the price charged by the actual provider. A network growth figure cannot answer those account-specific questions.
The Clearing House separately reports RTP network activity. Its 2026 row covers the first nine months, while its 2025 row covers a full year. Use those labels when comparing the series; a partial-year number is not a full-year forecast. Source: RTP network statistics.
Payment technology: distinguish the interface from the underlying payment
When evaluating a wallet or a mobile payment interface, ask which payment method ultimately funds the transaction. Record the interface and the payment method separately rather than assuming they are competing categories in the same market-share table.
Tokenization is another distinction worth making. EMVCo describes an EMV Payment Token as an alternative to the primary account number, with use that can be restricted to a merchant, device, or payment scenario. Its framework explains how tokens operate across the payment ecosystem. Source: EMVCo.
For a merchant or platform choosing an integration, ask which token type is being used, how recurring credentials are maintained, and what a future migration would require. A security specification alone does not establish your vendor's commercial terms or migration capabilities.
Review security by payment flow
Separate the controls needed for an in-person transaction from those needed for a card-not-present payment. Ask which authentication, credential, fraud-review and dispute processes apply to the actual flow. A national usage statistic is not evidence that a particular implementation is secure or that fraud will disappear.
How to use these statistics in your 2027 payment plan
Use national data to identify questions, then make decisions from your own operating evidence. We recommend reviewing four areas:
- Acceptance cost. Reconcile billed fees with transaction volume, card mix, and negotiated terms. Read the merchant account fee breakdown before comparing headline quotes.
- Customer choice. Compare conversion and usage by payment method. Treat any projected benefit from adding a method as a hypothesis until measured.
- Platform economics. Separate a software platform's payment revenue from processing volume and include the costs of service, integration, and ongoing operations.
- Operating ownership. Assign responsibility for statement review, payment support, reconciliation, and provider changes. A launch does not complete that work.
Turn payment data into an account-specific plan
Swipesum brings payment processing, merchant services, software, gateways, embedded payments, and a payments team into one operating model. Start with Swipesum Audit to examine processing statements, or talk to our payments team about the setup your business needs.
Frequently asked questions
Are these 2027 payment statistics?
No. These are available measurements checked in October 2026 for use in 2027 planning. Every metric identifies its observation period; none is presented as observed 2027 activity.
Is payment volume the same as payments market revenue?
No. Payment volume is money moved. Provider revenue is income earned from services. A market-size estimate needs a defined product category and revenue measure before it can be compared with another estimate.
Can industry averages show whether my processing fees are fair?
They provide context, but a useful comparison needs your fee schedule, transaction profile, and actual statements. Compare equivalent costs and services before making a provider decision.
Methodology and source notes
This resource combines public primary sources rather than a new Swipesum survey. The national payments study, consumer Diary, ACH Network report, and RTP network series measure different populations. Figures are rounded where stated; source documents remain authoritative. Our operating recommendations are analysis, not findings from those studies.