Best Credit Card Readers for Small Business: How to Choose
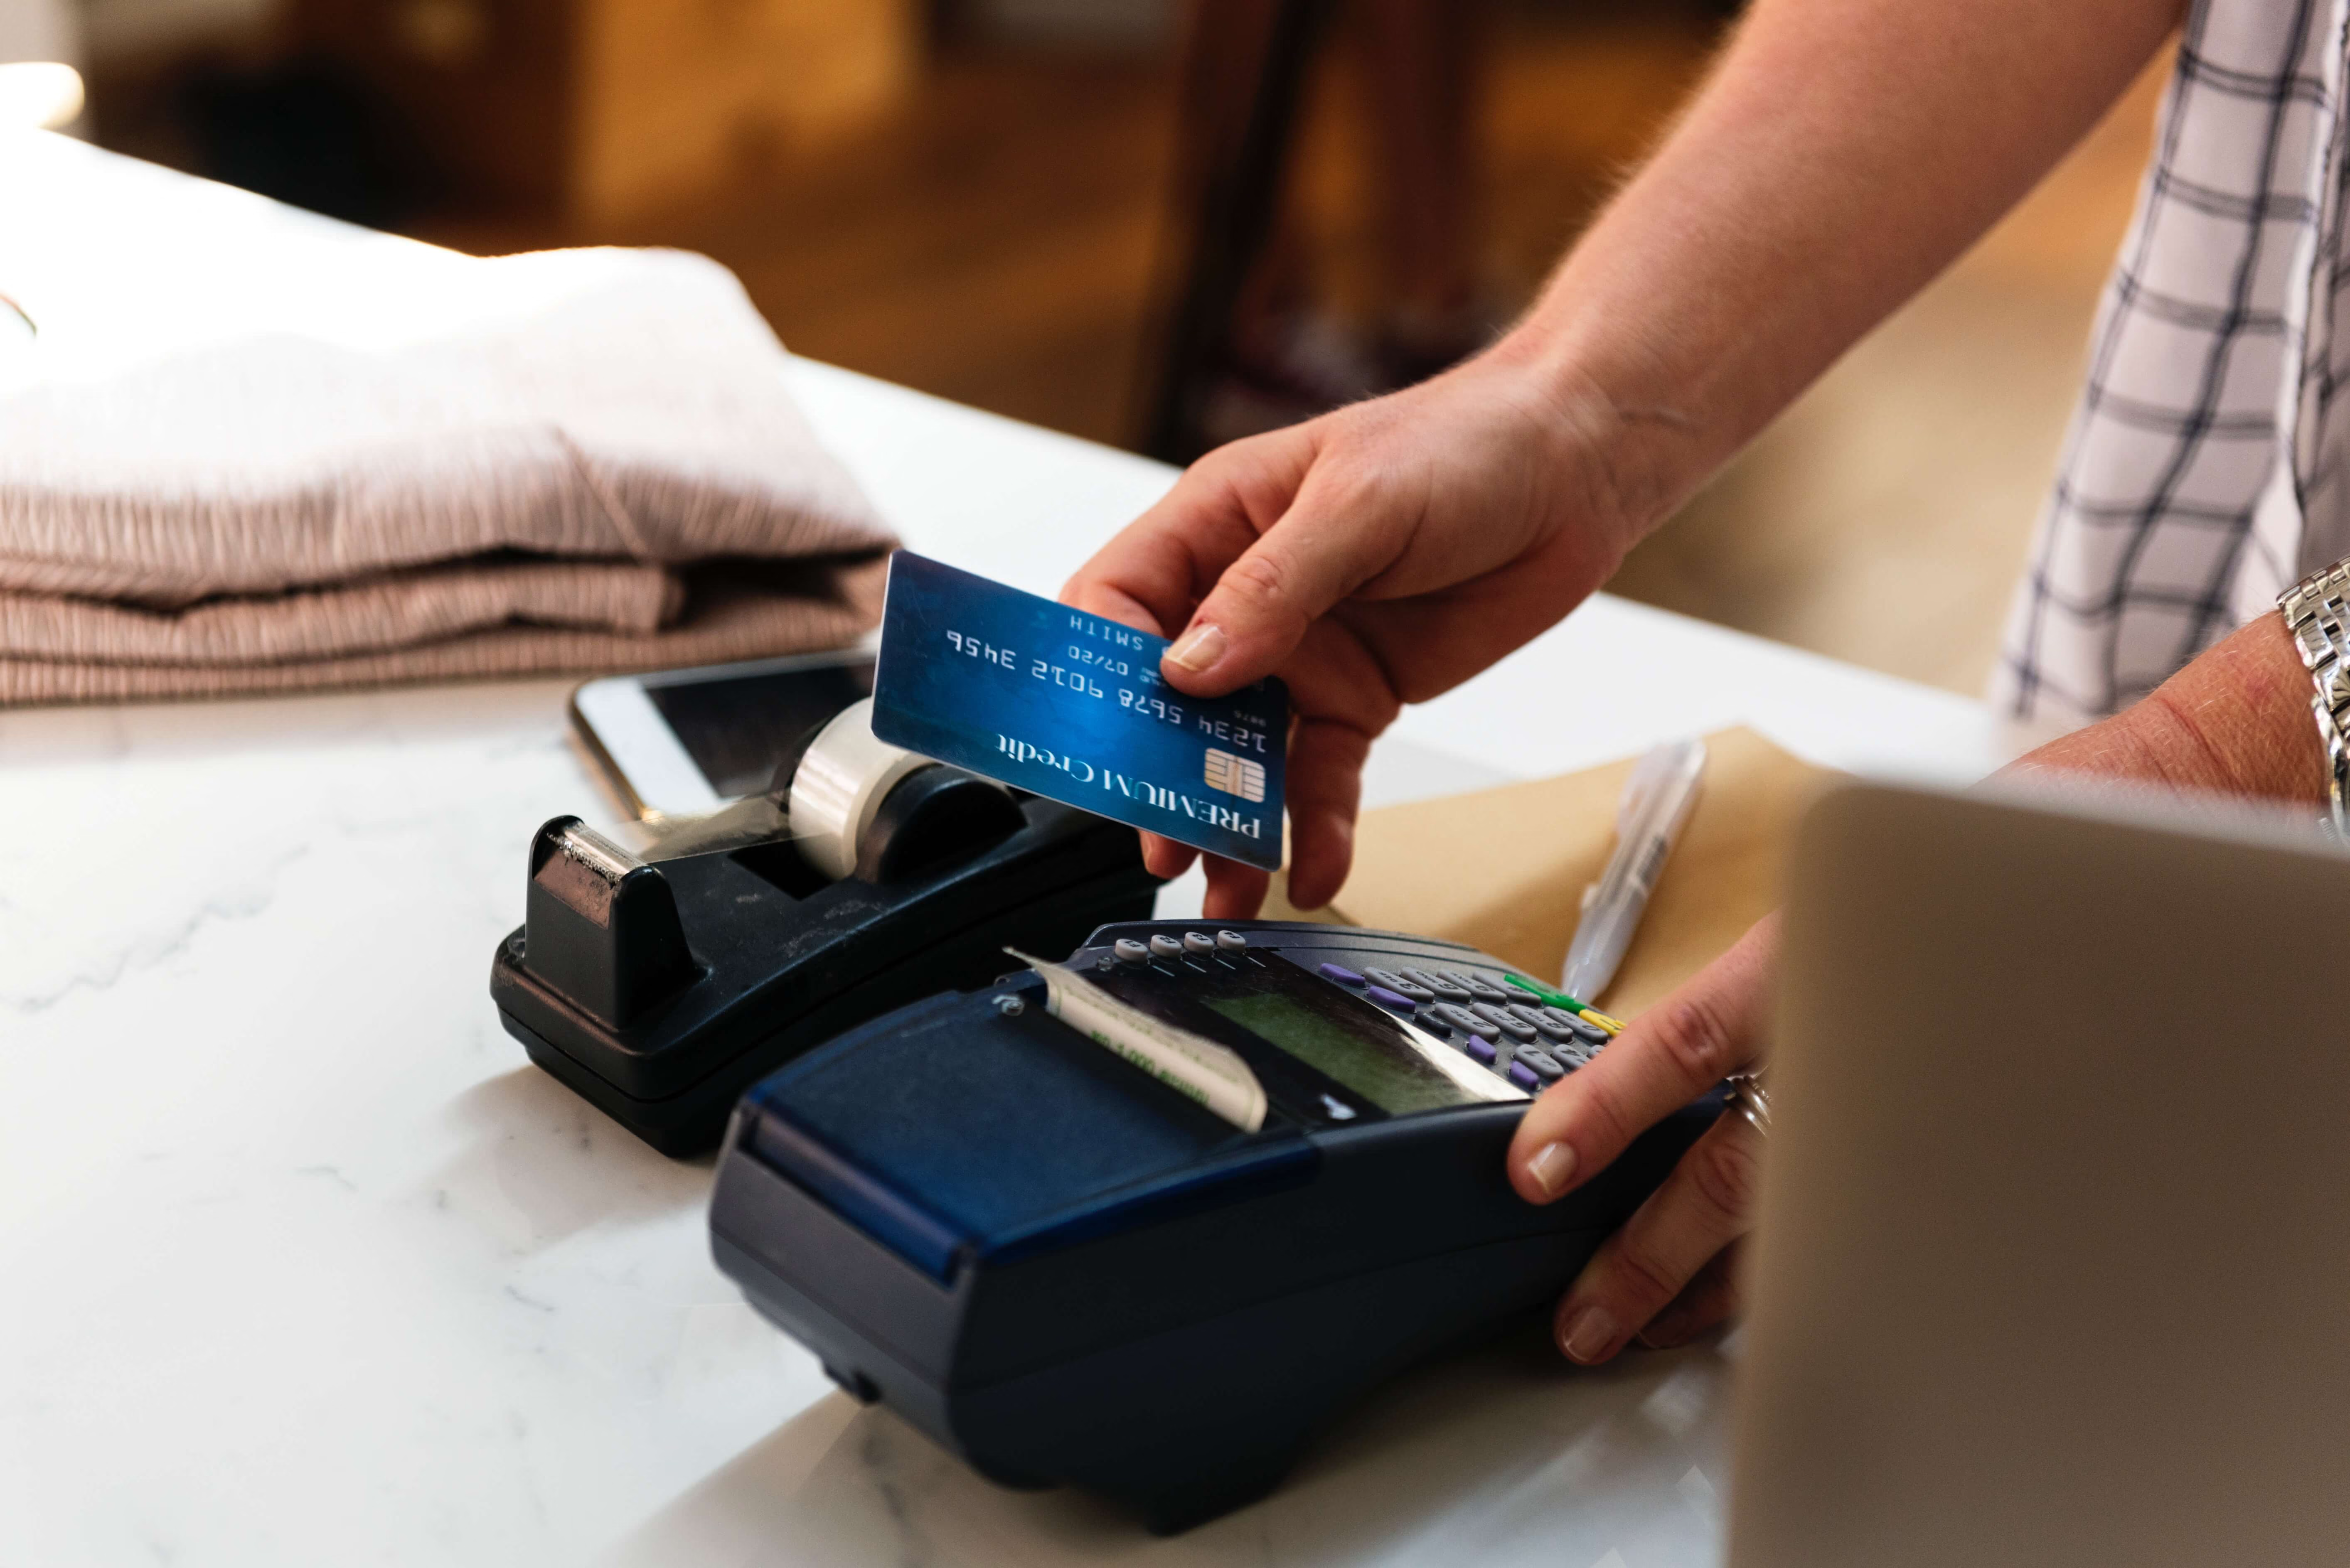
The best credit card reader for a small business is the one that works with its payment software, accepts the payment methods customers use and has a competitive total cost. A low device price alone does not establish the best deal: processing fees, software subscriptions, connectivity, contract terms and support can matter more over time.
For a simple mobile setup, compare a phone-connected chip and contactless reader. For a busy counter, restaurant or multiple locations, start with the POS workflow and approved hardware list. Swipesum helps businesses choose and implement the complete payment setup, including merchant accounts, hardware coordination and ongoing support.
Credit card reader options for small businesses
These examples use manufacturers’ published US product information and prices checked October 28, 2026. Prices are in USD; taxes, accessories, software and processing may add costs. This is a requirements-based comparison, not a hands-on device test or a universal ranking. Confirm the current offer and account eligibility before ordering.
Square Reader for contactless and chip: a compact phone or tablet setup
The second-generation contactless and chip reader is listed at $59. It supports chip cards and contactless payments through Square’s compatible app and mobile device. It can suit a small seller that wants to operate within Square’s payment and POS environment.
Distinguish this product from Square’s free first magstripe reader: the free swipe reader is not the same chip-and-contactless device. Check your device’s compatibility, the software plan you need and the applicable processing agreement. Square lists standard in-person pricing of 2.6% plus 15 cents per transaction on the product page; plans and custom agreements can differ. See Square’s current reader specifications and pricing.
PayPal Reader: a mobile POS option with a conditional first-reader offer
PayPal lists its Reader at a standard $79, with a $29 offer for one reader per eligible new business user, subject to availability and changing terms. It pairs with a compatible mobile device and PayPal’s POS app. The published card-present processing price is 2.29% plus 9 cents per transaction.
That introductory device price does not apply to every reader or buyer. Docks are separate, and the Reader should not be confused with PayPal’s standalone Terminal, listed at $199. Compare the checkout workflow, account terms and reporting you need against the current PayPal POS pricing and promotion conditions.
Helcim Card Reader: an interchange-plus option
Helcim lists its Card Reader at $199 and uses interchange-plus processing with volume-based pricing. The current product supports chip and contactless payments, Wi-Fi and built-in mobile data. Its published mobile data option costs $7 per month in the US; Wi-Fi does not add that data charge. An approved Helcim merchant account is required.
This option is worth comparing when you want to evaluate processing economics alongside hardware rather than choose solely on an introductory device price. Helcim states that this reader does not support offline payments. Verify your exact device, app and integration requirements against Helcim’s current product details.
Reader, terminal, POS system or Tap to Pay?
- Mobile reader: usually works with a phone or tablet running a payment app. Check the operating system, connection method, battery life and who owns the mobile device.
- Standalone terminal: runs its payment workflow on the device. Confirm whether a printer, scanner, data connection and business software are included or extra.
- Integrated POS hardware: exchanges payment amounts and results with your register, restaurant software or other business system. The POS provider’s certified device and processor combinations determine your choices.
- Tap to Pay on a compatible phone: may let you accept eligible contactless cards and wallets without a separate reader. It does not give you every function of a chip reader, receipt printer or full POS system. Check provider, phone and market eligibility.
For an occasional market stall, a compact reader may be enough. A restaurant may need pay-at-table, tipping and reliable order synchronization. A retailer with several checkout lanes may need integrated devices, receipt printing, shared inventory and a defined replacement process. Choose the workflow before the model.
Check compatibility before buying a card reader
A card reader is not automatically compatible with every processor or POS system. Even when the physical model looks identical, encryption, firmware, account provisioning and the certified integration can affect whether it works in your environment.
Ask the seller and software provider to confirm the exact model and configuration in writing. If you are keeping an existing POS, have them identify the supported gateway, processor and connection method. Ask whether a used device can be transferred or reconfigured, what that costs and who is responsible for the work. Do not purchase unsupported equipment assuming it can be unlocked later.
Businesses building payments into their own software should also review integrated payment solutions for software platforms. A suitable standalone reader does not establish that its integration can support your application.
Compare the full cost, not just the hardware price
Build a 12-month cost comparison using the same card sales, transaction count, payment methods and software requirements for each proposal. Include:
- Purchased hardware, shipping, installation, docks, printers and replacement units.
- Processing charges, including percentage and per-transaction fees, with card-present and keyed or online payments separated.
- POS subscriptions, extra registers, gateway charges, cellular service and other recurring account fees.
- Refund, dispute and other conditional fees, plus any minimums or early termination obligations.
- Lease or financing payments, ownership at the end of the term and equipment return requirements.
For a hypothetical business taking $20,000 across 1,000 transactions monthly, a 0.20 percentage-point rate difference changes percentage fees by $40 per month. A separate 5-cent difference per transaction adds $50 per month. Together, those differences equal $1,080 over 12 months before hardware and other charges. This illustrates why a discounted reader can still come with a higher overall cost; it is not a savings estimate for your business.
Flat-rate and interchange-plus quotes need different comparisons. A quoted markup above interchange is not the complete processing rate. Use the same statement and card mix to compare the expected total, and confirm the agreement instead of relying on a sales headline. Swipesum can review a processing statement and help evaluate the fees alongside the hardware requirements.
What to test before replacing your payment hardware
- Run the actual checkout. Test a chip payment, contactless card and mobile wallet, plus tips or other required workflows. Confirm amounts flow correctly between the POS and terminal.
- Test reversals. Verify a void and a refund, including permissions and whether the result appears correctly in the POS and payment reporting.
- Check connectivity. Test where the device will be used. Ask what happens when Wi-Fi or cellular service fails. Offline acceptance is product-specific and can leave the merchant responsible for later declines or disputes.
- Verify settlement. Match a batch to the payment report and bank deposit, allowing for the agreed funding schedule and fee deductions.
- Confirm staff access. Set appropriate permissions and train staff on receipts, charging, refunds, error messages and escalation.
- Plan a replacement. Identify the support owner, replacement lead time, warranty, spare-device process and any migration or token portability limitations.
For multiple locations, inventory each store’s hardware, software version, merchant account and network requirements before deployment. Pilot the setup, schedule the rollout and review the first statements after go-live.
How Swipesum helps with hardware selection and implementation
Hardware decisions affect merchant accounts, funding, software and support. In one published 56-location retail payment migration, Swipesum coordinated the processing relationship, merchant accounts, hardware and store transition, then continued statement review and fee escalation after launch. That case illustrates the implementation work behind the devices; it does not promise a particular result for every rollout.
Swipesum can help compare compatible options, negotiate the payment relationship and coordinate implementation. For a new setup or replacement project, call (844) 312-0589 or email save@swipesum.com. For help with an existing payment setup, contact Swipesum support at (844) 356-9905 or support@swipesum.com. Available account actions depend on the provider relationship and your authorization.
Credit card reader questions
What is the best credit card reader for a small business?
Start with compatibility and how you sell. A phone-connected reader may suit mobile or occasional sales; an integrated terminal may be a better fit for a busy checkout. Compare the full payment agreement, required software and support instead of choosing on device price alone.
Can I get a free credit card reader?
Some providers offer free or discounted hardware with conditions. Confirm the payment methods the device supports, eligibility, processing terms and any return or contract obligations. A free magstripe reader is not the same product as a chip-and-contactless reader.
Can I use one card reader with any payment processor?
Do not assume that you can. Compatibility depends on the device configuration, payment application, encryption and certified provider connections. Get written confirmation before purchasing or changing processors.
Do I need a separate reader to accept payments on my phone?
Some providers support Tap to Pay on eligible phones for contactless acceptance. You may still need separate hardware for chip insertion, printed receipts or other operational requirements. Confirm the supported phone and app combination.